You Wrote It Off Federally—So Why Is New York Still Taxing It?
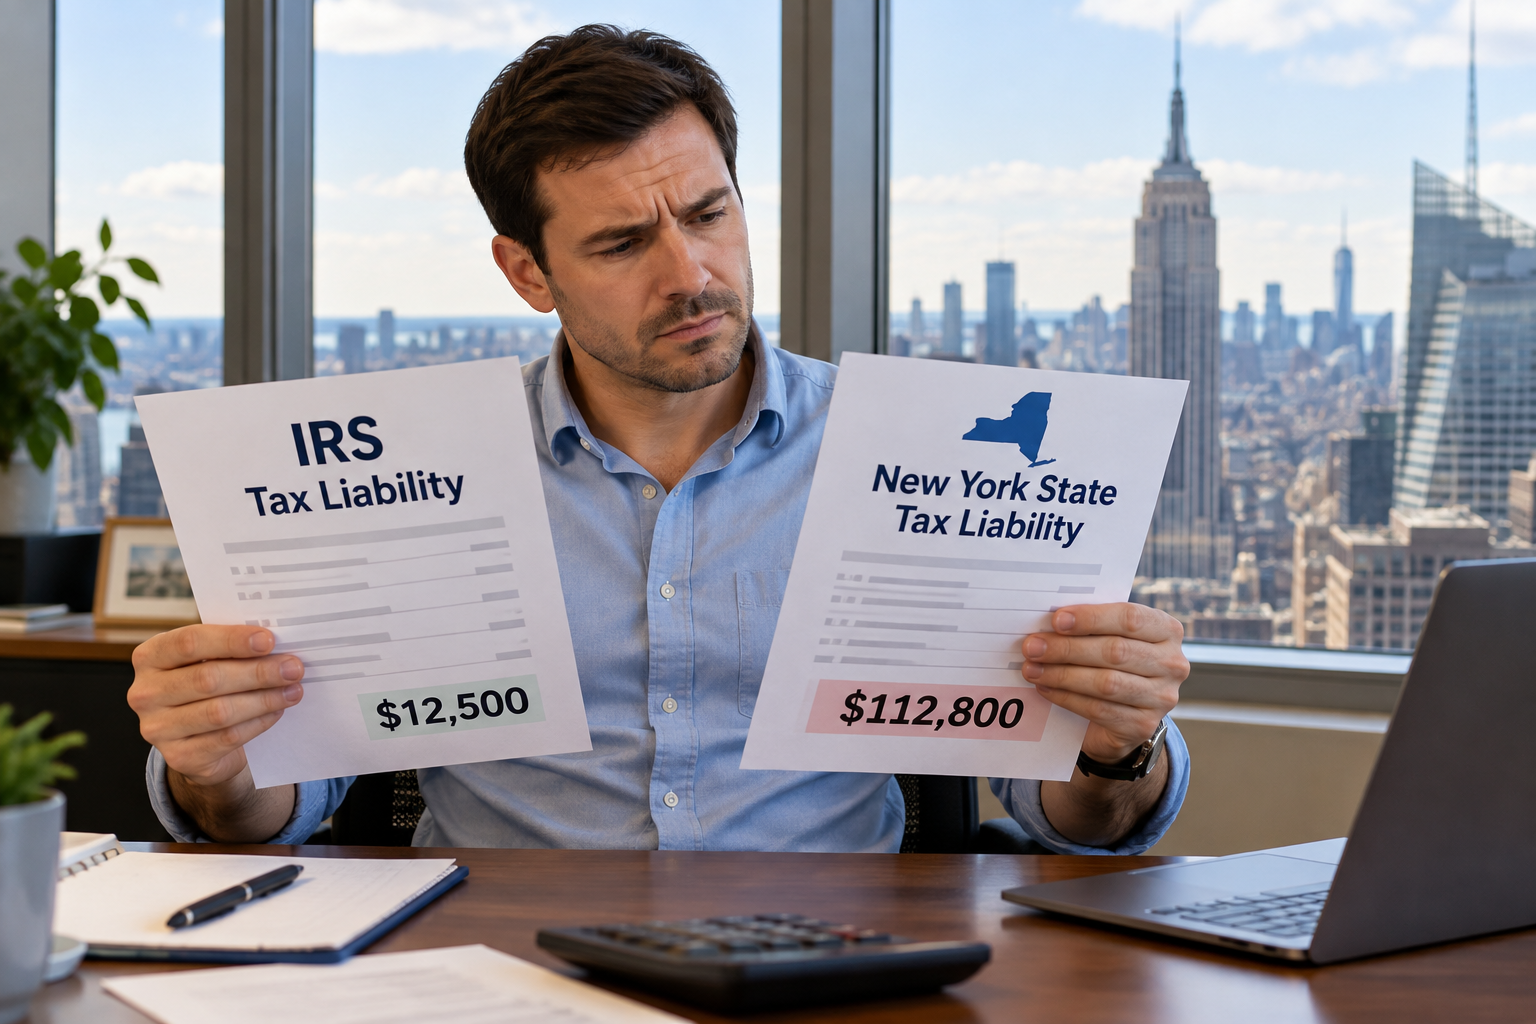
One of the more confusing parts of New York bonus depreciation is that your federal tax return and your New York tax return can tell two very different stories about the exact same business purchase.
We just finished a tax return for a new client who owns an S corporation, and this issue had a very real impact. Because of the federal depreciation deductions taken by the S corporation, the client’s federal pass-through income was relatively low. But New York did not allow the same depreciation treatment. When we prepared the owner’s personal New York tax return, we had to add back the depreciation difference, which increased the taxable S-corporation income flowing through to the New York personal return by more than $100,000.
So while this may sound technical and you may be thinking, “Hey, this is all happening inside my S corp. Why do I need to worry about it?” there can be a very real consequence on your personal New York tax return. Bonus depreciation taken by your S corporation can result in significantly different federal and New York taxable income flowing through to you personally.
How Federal and New York Bonus Depreciation Became So Different
For qualifying property acquired and placed in service after January 19, 2025, federal law generally provides a 100% additional first-year depreciation deduction unless an applicable election is made.
In plain English, qualifying property can potentially be written off federally in the year it is placed in service rather than depreciated over several years.
New York has a different rule. New York generally does not conform to the federal special depreciation rules under IRC Section 168(k). For individual taxpayers and pass-through business owners, New York Form IT-398 is used to calculate the difference between the federal deduction and the depreciation New York allows.
So you can have:
Federal tax return: Large depreciation deduction immediately.
New York tax return: Smaller depreciation deduction this year, with additional depreciation deductions potentially coming in later years.
The asset did not disappear for New York purposes. The timing of the deduction is simply different.
New York Bonus Depreciation Is Often a Timing Difference
This is the most important concept to understand.
Suppose a business buys qualifying equipment for $100,000 and, for simplicity, receives a $100,000 federal bonus depreciation deduction. The federal tax basis may effectively be reduced immediately.
New York may instead require the federal bonus depreciation adjustment and then allow depreciation using its own calculation over time.
So in the first year, your federal taxable business income could be substantially lower than your New York taxable income. In later years, the situation can begin to reverse because New York may continue allowing depreciation deductions while there is little or no federal depreciation left on that asset.
That is why we think of this primarily as a timing difference.
Section 179 and New York Bonus Depreciation Are Not the Same Thing
We sometimes hear people use “Section 179,” “bonus depreciation,” and “writing it off” as though they all mean the same thing. They don’t.
Section 179 is a separate federal election that allows qualifying businesses to expense eligible property, subject to several rules and limitations.
For 2025, the federal Section 179 limit is $2.5 million, subject to a phaseout once qualifying property placed in service exceeds $4 million. The actual Section 179 deduction can also be limited by taxable business income.
Bonus depreciation works differently. For qualifying property acquired and placed in service after January 19, 2025, federal bonus depreciation is generally 100%. Taxpayers can make certain elections concerning bonus depreciation, and the rules do not operate exactly like Section 179.
That distinction matters when we are deciding how to depreciate a significant purchase.
The question should not simply be: “Can we write this off?” The better questions are:
- Does the property qualify?
- Should we use Section 179?
- Should we use bonus depreciation?
- Should we elect out of bonus depreciation for a particular class of property?
- What happens on the New York return?
- What will our taxable income look like this year and in future years?
Sometimes the biggest possible first-year deduction is useful. Sometimes spreading the deduction over several years produces a better overall result. Tax planning should answer that question before simply clicking the button for the largest available deduction.
New York Bonus Depreciation Can Make Your Tax Return Look Strange
Here is another situation we see. Your profit-and-loss statement might show one amount.
Your federal tax return might show substantially less taxable income because of accelerated depreciation. Your New York return might then show taxable income increasing again because New York does not allow the same federal depreciation deduction.
Nothing is necessarily wrong. You may simply be looking at three different accounting and tax measurements. That is why looking only at “profit” without understanding which profit somebody is talking about can cause confusion.
New York Bonus Depreciation Can Matter Beyond This Year’s Tax Bill
Accelerated depreciation is useful, but we do not like looking at it in isolation. A major depreciation deduction can affect conversations that have nothing to do with simply calculating this year’s tax return.
Financial statements
Tax depreciation and book depreciation may be different. So a huge deduction on the tax return does not necessarily mean your financial statements will show the same expense.
EBITDA
Depreciation is generally added back when calculating EBITDA, which means someone evaluating the operating performance of the company may view the purchase differently from the tax return.
Bank and loan discussions
A lender may start with financial-statement income and then make its own adjustments. If you are applying for financing, buying property, or renewing a credit facility, we want to understand what numbers the lender is actually reviewing.
Selling the business
Depreciation can also matter when a business or its assets are eventually sold.
The fact that you received a large deduction when purchasing an asset does not necessarily mean that benefit comes without future consequences. Depending on what is sold and how the transaction is structured, depreciation recapture and differences in tax basis can become important.
This is one reason we encourage clients who may sell a business in the next few years to start planning well before an actual buyer appears.
A $100,000 Purchase Does Not Automatically Mean a $100,000 Tax Savings
This deserves its own section because “write-off” is probably one of the most misunderstood phrases in small-business taxes. If you buy $100,000 of equipment and deduct $100,000, you have not received $100,000 from the government.
You have generally reduced taxable income by $100,000.The actual tax savings depend on your tax rates, the entity structure, other income and deductions, state taxes, limitations, and other facts.
And in New York, the federal and state timing may be different.
So before spending money because somebody told you that you can “write it off,” start with a much simpler business question: Do you actually need the thing?
A tax deduction can make a necessary investment less expensive. It generally does not turn an unnecessary purchase into a good investment.
What New York Business Owners Should Review Before Year-End
If you are considering a significant equipment purchase or business improvement, we want to look at it before the year is over.
Ideally, we should know:
- What you are purchasing
- How much it costs
- Whether it is new or used
- When it will be ready and available for business use
- How much taxable income you expect for the year
- Whether Section 179 or bonus depreciation may apply
- What the New York depreciation treatment will be
- Whether you expect significantly more or less income next year
- Whether a sale, loan, or other major business transaction is coming
The goal is not simply to create the biggest deduction possible. The goal is to understand what that deduction actually accomplishes.
Planning a Large Business Purchase?
If you’re considering a large purchase for your business—or you’ve already made one—and you’re wondering how bonus depreciation could affect your personal New York State tax return, we can help you understand the federal and New York tax impact.
Click here to contact My Fiscal Office and start the conversation.