New York City Domicile: The 183-Day Rule Is Only Half the Story
We are expecting to see New York City Domicile come up much more frequently because New York City now has a non-primary residence property surcharge, commonly referred to as the pied-à-terre tax, on certain higher-value homes, condominiums and cooperative apartments that are not used as a primary residence.
That creates an interesting tax situation. A property owner may want to tell the New York City Department of Finance that the NYC apartment is their primary residence in order to qualify for an exemption from the property surcharge, while at the same time filing a New York income tax return claiming that they are not a New York City resident. Those two positions are not necessarily governed by identical rules, but taking seemingly inconsistent residency positions with different New York taxing authorities is something that should be considered very carefully and thoroughly documented.
The Department of Finance’s exemption process specifically asks taxpayers to provide evidence supporting primary-residence status, which can include their most recently filed federal or state income tax return.
I expect this new surcharge will result in considerably more attention being paid to residency claims going forward. In fact, we recently created a detailed residency worksheet for a client who maintains both an upstate home and a New York City apartment.
Instead of simply putting “NYC nonresident” on the tax return, we documented the facts supporting that position: where the clients actually live, how the two homes are used, their family and personal connections, driver’s licenses and vehicle registrations, voting registration, employment connections, and a contemporaneous record of their New York City days. The goal is simple: if New York questions the residency position later, we want to be able to explain why we took that position and what facts supported it when the return was filed.
New York City Domicile Comes Before Counting Days
For tax purposes, domicile essentially means your one true, permanent home, the place you consider home and intend to return to when you are away. You can own or use multiple residences. You can have a house upstate, an apartment in Manhattan, a vacation house somewhere else and spend substantial amounts of time at each.
But for tax purposes, you generally have only one domicile. New York describes domicile as your permanent and primary residence—the place you intend to return to or remain in after being away.
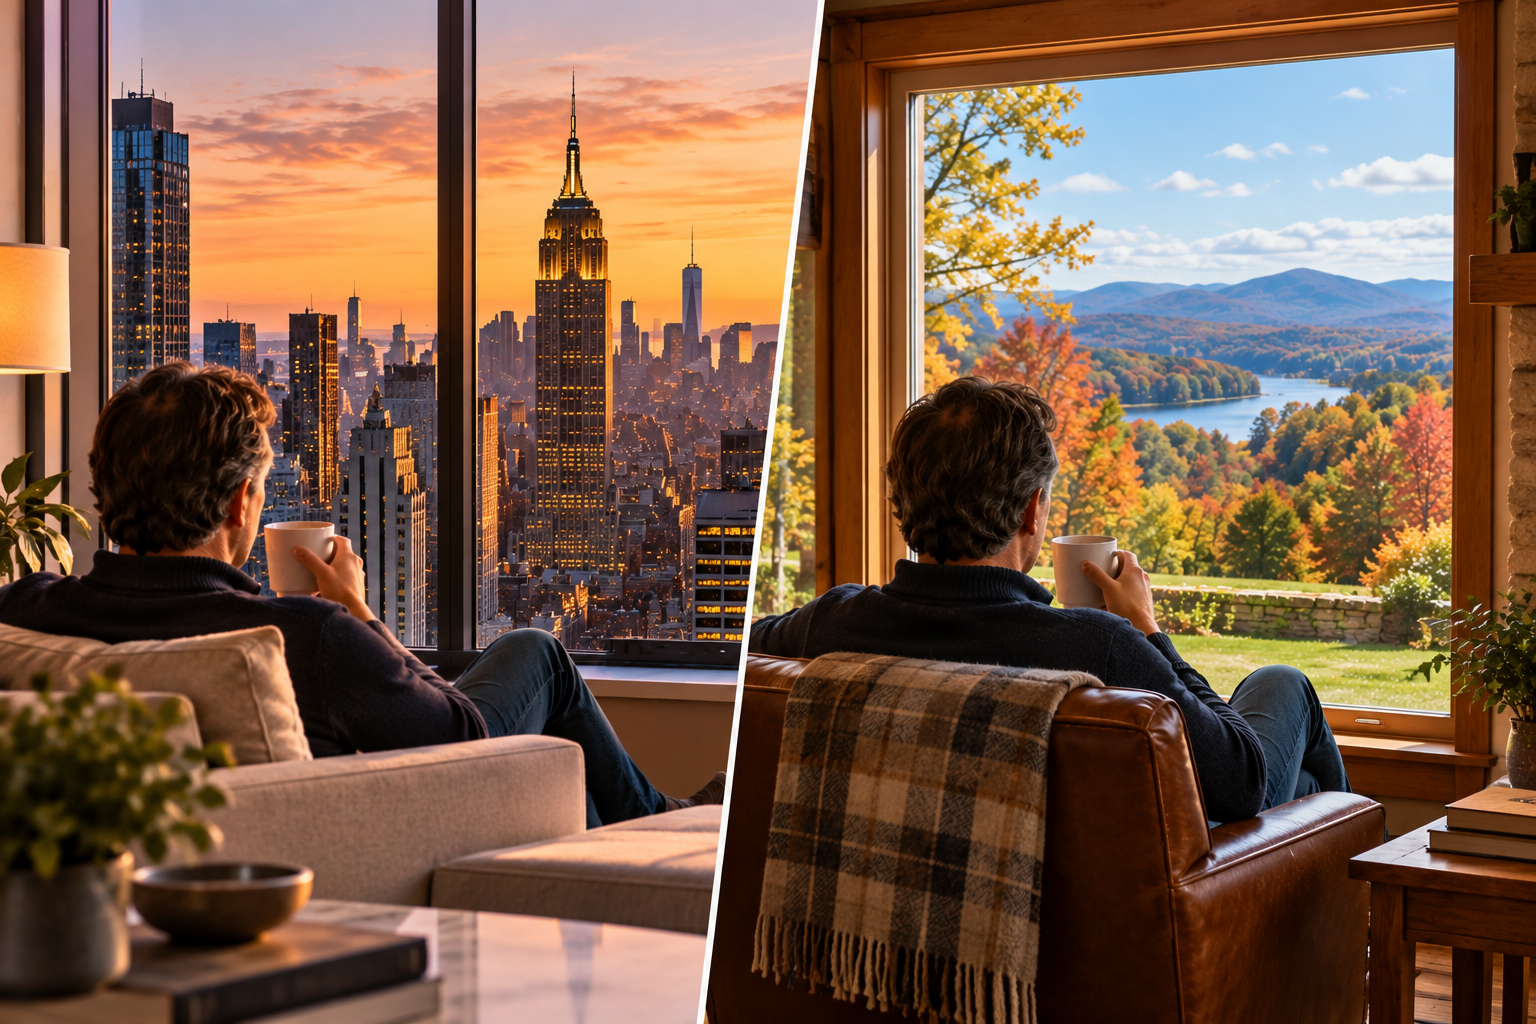
So if you own a house upstate and maintain an apartment in New York City because you work in the city, the first question is Which one is really home?
That answer comes before we start counting NYC days.
Why New York City Domicile Matters More Than the 183-Day Rule
There are essentially two different ways you can be considered a New York City resident for income tax purposes.
The first is domicile.
If your domicile is New York City, you are generally a New York City resident regardless of whether you spent 100, 120 or 180 days physically in the city.
The second is what is commonly called the statutory residency test.
Even if your domicile is somewhere outside New York City, you can still be treated as an NYC resident if you maintain a permanent place of abode in the city and spend 184 days or more in New York City during the year. New York applies the same basic residency framework to New York City that it does to New York State.
That is why saying, “I was in New York City fewer than 184 days” does not answer the entire question. If New York City remains your domicile, the day count generally does not rescue you.
What Determines Your New York City Domicile?
This is where residency becomes much more fact-specific. New York does not determine domicile based on one form, one address or one checkbox. It looks at how you actually live.
New York’s own nonresident audit guidance identifies major factors such as the nature and use of your homes, your active business involvement, where you spend your time, where you keep items that are particularly important to you, and your family connections. The factors are considered together rather than mechanically counting how many point toward one location or another.
For someone comparing an upstate home with a New York City apartment, we would want to understand questions such as:
- What is the nature and size of each residence, and how is each actually used?
- Where do you spend your time when you do not need to be in New York City for work?
- Where is your personal and family life centered?
- Where does your spouse generally live?
- Where do you spend weekends, holidays and vacation time?
- Where do you keep the possessions that are personally most important to you?
- Where are your social, community and personal connections?
- How significant are your employment and business connections to New York City?
- Does the NYC apartment primarily function as a convenient place to stay for work, or does it function as your actual home?
- When you have a choice about where to be, where do you normally go?
No single answer necessarily decides the issue. We are looking at the overall pattern of your life.
Changing Your Address Does Not Automatically Change Your New York City Domicile
People sometimes focus heavily on administrative items. They change their driver’s license to the upstate address. They move their voter registration. They register their car upstate. They change their mailing address. Those things can be useful. But they are not enough by themselves.
New York explicitly says changing items such as voter registration does not, by itself, establish a change of domicile. The state looks at all aspects of the person’s life.
Think of it this way – Changing your driver’s license tells New York where you say you live. But your actual lifestyle tells New York where you really live. The second one is much more important.
Changing an Existing New York City Domicile Requires Stronger Evidence
There is another wrinkle that becomes especially important for someone who has historically lived in New York City. Domicile generally continues until it is changed.
If your established domicile was previously New York City and you are now claiming that you moved your domicile upstate, New York says the person asserting the change has the burden of demonstrating it with clear and convincing evidence.
That means this is more than simply deciding one year that you would prefer to use the upstate address on your tax return. There needs to be a genuine change in where your life is centered.
For example, if you buy a substantial house upstate but still spend most weekends in Manhattan, your spouse remains primarily in the city, your personal possessions remain there and the upstate house functions mostly as a weekend property, changing your driver’s license may not accomplish much.
On the other hand, the facts may look very different if the upstate house is where you and your spouse actually live, where your personal life is centered, where you return when you do not need to be in the city, and the city apartment is principally maintained because commuting home every night is impractical.
Working in New York City Does Not Automatically Establish New York City Domicile
Employment is certainly part of the analysis, and someone who works in New York City five days a week obviously has a significant connection to the city. But employment alone does not automatically determine domicile.
It is entirely possible for someone to genuinely live outside New York City, commute into the city for work and maintain a small NYC apartment because of the commute. The important distinction is what happens when work does not dictate where that person needs to be and these facts can be much more revealing than the address printed on your W-2:
- Where do you go on Friday night?
- Where do you normally spend Saturday and Sunday?
- Where do you spend holidays?
- Where does your family live?
- Where are the things that make a house your home?
Once New York City Domicile Is Established, Then We Count Days
Assume we are comfortable that the upstate house really is your domicile. Now we move to the second test.
If you maintain an apartment or another permanent place of abode in New York City for substantially all of the year, you generally need to spend 183 days or fewer in New York City to avoid meeting the 184-day statutory residency threshold.
And this is where people sometimes make another mistake, it is not simply a count of nights spent sleeping in your NYC apartment.
Generally, any part of a day physically spent in New York City counts as a New York City day for this test. So if you commute into Manhattan Tuesday morning, work Tuesday and return upstate Tuesday evening, Tuesday generally counts as an NYC day even though you never slept in the city.
For someone who works regularly in New York City, that means the day count can add up surprisingly quickly.
Documentation Matters
If you are going to file as a New York State resident but not a New York City resident while maintaining a NYC apartment, this is an area where good records matter. Do not try to recreate your entire year from memory the following April.
Calendar records, travel records, credit-card activity, toll information and other contemporaneous records can help establish where you were during the year. New York’s audit guidelines specifically recognize documentation such as contemporaneously maintained calendars or diaries when reviewing residency.
The closer you expect to come to 184 NYC days, the more important that documentation becomes.
The Two Questions We Need to Answer
For a New York State resident with an upstate home and a New York City apartment, we ultimately want to be comfortable supporting two separate conclusions:
First: My real and permanent home is outside New York City, and the facts of my life support that conclusion.
Second: I spent no more than 183 days physically present in New York City during the year.
If both are supportable, there is a much stronger basis for filing as a New York State resident who is not a New York City resident.
That distinction can be important because New York City residents are subject to NYC personal income tax on their income, while NYC nonresidents generally are not subject to the city’s personal income tax merely because they work there.
The important takeaway is that residency planning should not start with, “How many days was I in New York City?” It should start with “Where is my real home?”
Once we can answer that question confidently, then we get out the calendar.
Have Two Homes and Not Sure About Your NYC Residency?
If you maintain a New York City apartment but consider your permanent home to be somewhere else, don’t wait until your tax return is being prepared to think about residency.
Your domicile, your New York City day count, and the records supporting both should tell a consistent story. And with New York City’s new non-primary residence property surcharge adding another reason for the City to determine whether an apartment is—or is not—someone’s primary residence, documenting that story has become even more important.
At My Fiscal Office, we can help you review the facts, identify potential inconsistencies, and document the basis for your New York City residency position before your return is filed.
Have questions about your New York City residency? Contact My Fiscal Office to schedule a tax planning conversation.