New York SALT Tax Workarounds: PTET vs. ECEP and NYC Options
We love being in New York City, but running a business here can get complicated. We know because we run a business here, too. One area that deserves more attention is New York SALT tax workarounds. These programs can help eligible business owners reduce the federal tax impact of the limit on deducting state and local taxes.
New York actually offers two different approaches, and New York City has its own version of one of them.
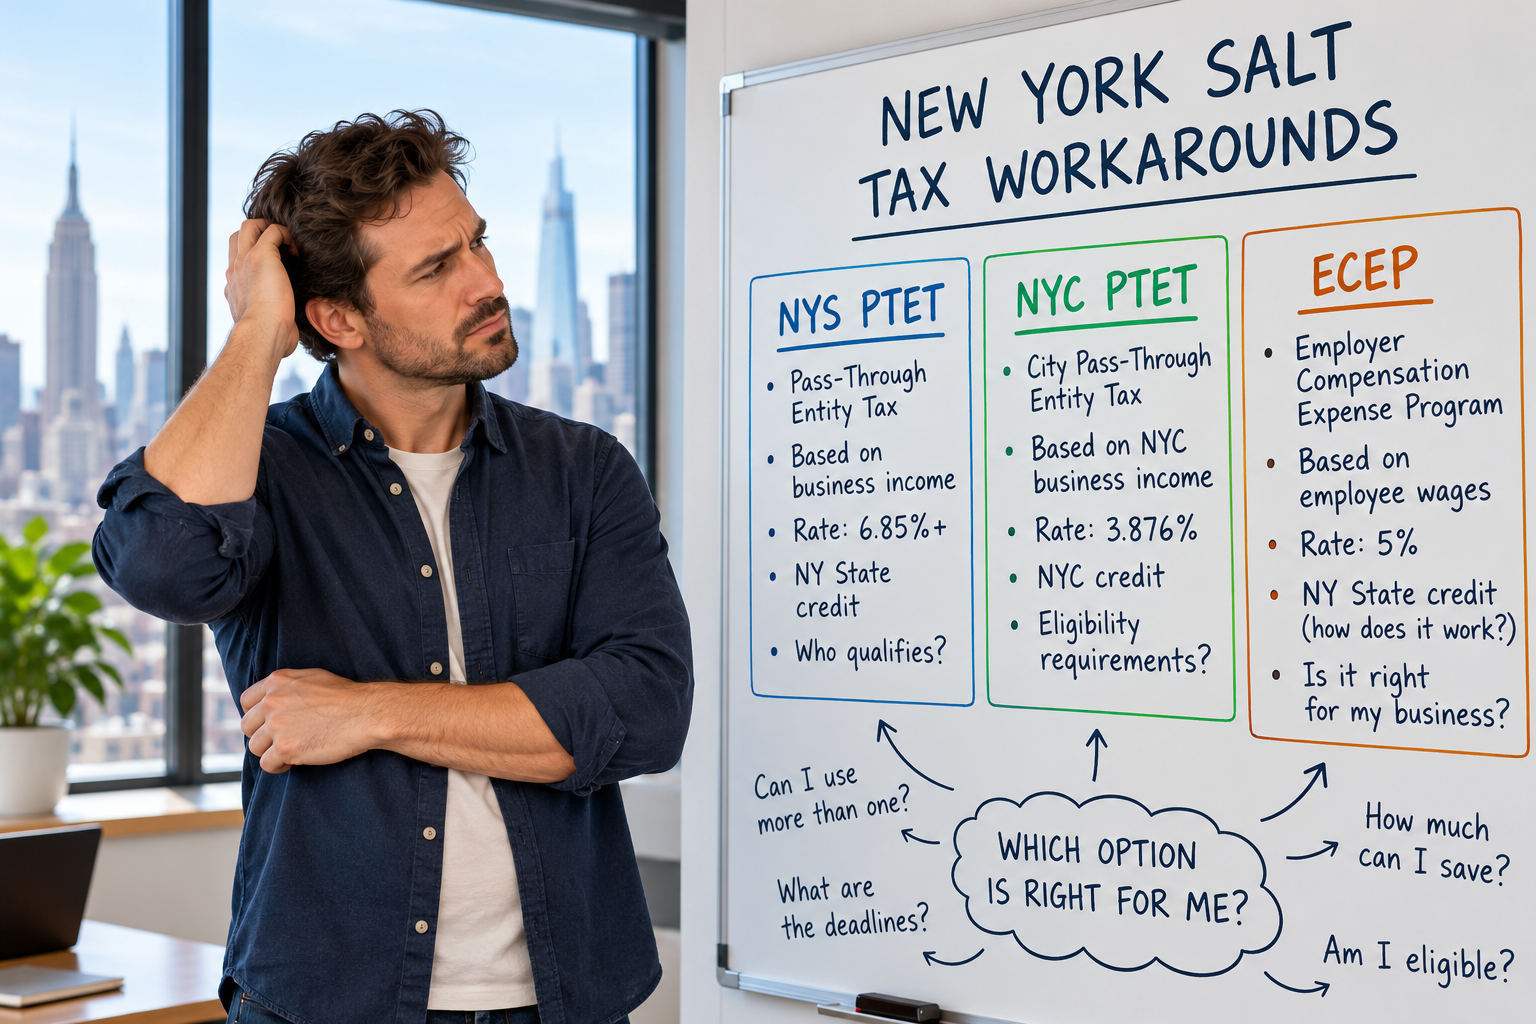
The three programs are:
- New York State Pass-Through Entity Tax (NYS PTET)
- New York City Pass-Through Entity Tax (NYC PTET)
- New York State Employer Compensation Expense Program (NYS ECEP)
They sound similar, but they work very differently. And for certain business owners, particularly S corporation shareholders, using more than one program may make sense.
Let’s explain how they work.
Why New York SALT Tax Workarounds Exist
SALT stands for state and local taxes.
On your federal personal income tax return, you may be able to deduct certain state and local income taxes and property taxes if you itemize deductions. However, federal law limits how much you can deduct.
For 2026, the federal SALT deduction limit is generally $40,400 for eligible taxpayers, subject to income-based limitations and filing-status rules.
For business owners in New York, particularly New York City, reaching that limit isn’t difficult. Between New York State income taxes, New York City income taxes, and real estate taxes, the total can be substantial.
The problem is that once you reach your applicable federal SALT deduction limit, additional personal state and local tax payments generally don’t provide another federal itemized deduction.
That’s where New York’s workaround programs come in.
Rather than paying certain taxes personally, qualifying businesses can pay specific taxes at the business level. Those payments may become deductible business expenses for federal income tax purposes, with corresponding state or city personal income tax credits.
That distinction can create meaningful tax savings.
New York SALT Tax Workaround #1: NYS PTET
The New York State Pass-Through Entity Tax, commonly called PTET, is available to eligible partnerships and S corporations.
Instead of the business owner paying all their New York income tax personally, the business elects to pay tax on qualifying pass-through income.
The business generally deducts the PTET payment for federal income tax purposes.
The owner then receives a corresponding New York State personal income tax credit.
How NYS PTET Works
Let’s assume you own an S corporation that has $100,000 in qualifying New York taxable profit.
At the first PTET tax bracket, the rate is 6.85%.
That produces an illustrative PTET liability of:
$100,000 × 6.85% = $6,850
The S corporation pays the $6,850 and generally receives a federal tax deduction.
You receive a New York State personal income tax credit based on your share of the PTET.
New York also requires an adjustment to account for the PTET deduction taken at the federal level.
The real benefit is the potential federal deduction that otherwise might have been limited under the personal SALT deduction rules.
Who Benefits From NYS PTET?
This program is particularly relevant for:
- S corporation shareholders
- Partners in partnerships
- Owners of profitable pass-through businesses
- Owners whose personal state and local taxes exceed their federal SALT deduction limit
An important distinction: a single-member LLC taxed as a sole proprietorship generally cannot elect PTET on its own. The entity must qualify under the program’s rules.
New York SALT Tax Workaround #2: NYC PTET
New York City has its own Pass-Through Entity Tax.
This is separate from the New York State PTET.
The NYC PTET rate is 3.876% of qualifying city pass-through income.
Like the state program, the business generally receives a federal deduction for the tax payment, and qualifying owners receive a corresponding New York City personal income tax credit.
Example of NYC PTET
Let’s use the same S corporation with $100,000 of qualifying profit.
The illustrative NYC PTET calculation would be:
$100,000 × 3.876% = $3,876
That is potentially another federal business-level deduction.
If the business qualifies for both NYS PTET and NYC PTET, the two programs can work together.
However, eligibility is important.
For an S corporation to elect NYC PTET, it generally must have only New York City resident shareholders and meet the applicable New York State PTET requirements.
Partnerships have different eligibility rules.
Does NYC PTET Replace the City’s S Corporation Business Tax?
No, and this is an important distinction.
New York City does not recognize federal S corporation treatment in the same way New York State does.
An S corporation operating in NYC may still be subject to the city’s General Corporation Tax.
The NYC PTET is a separate election and does not eliminate that corporate-level tax.
So when we’re reviewing an NYC S corporation, we need to look at the business’s city tax obligations along with the potential benefits of PTET.
New York SALT Tax Workaround #3: ECEP
The Employer Compensation Expense Program, or ECEP, is probably the least understood of these three options.
Unlike PTET, which is based on business income, ECEP is based on employee wages.
This difference makes it particularly interesting for some S corporation owners.
Under ECEP, an employer voluntarily elects to pay the Employer Compensation Expense Tax, or ECET.
The tax is generally 5% of covered New York employee wages exceeding $40,000 annually.
The employer generally receives a federal deduction for the tax paid.
The covered employee may then claim a New York State personal income tax credit.
However, unlike PTET, the ECEP credit is not necessarily equal to the employer tax paid. The credit calculation incorporates the employee’s effective New York State income tax rate.
Example of How ECEP Works
Let’s assume you own an S corporation and receive a $150,000 W-2 salary.
Your employer’s illustrative ECEP calculation would be:
Annual salary: $150,000
Less annual wage exclusion: $40,000
Wages subject to ECET: $110,000
$110,000 × 5% = $5,500
The S corporation would pay $5,500 in ECET, generally creating a federal business deduction.
You would then calculate the corresponding personal New York State credit under the program’s rules.
Because the credit is not a simple dollar-for-dollar offset, we need to calculate the actual combined federal and state impact before deciding whether the election makes financial sense.
Why ECEP May Matter for S Corporation Owners
Consider an S corporation that pays its owner a substantial salary but has relatively modest profit.
PTET is tied to qualifying business income.
ECEP is tied to qualifying wages.
That means an owner who receives a large W-2 salary may have an ECEP opportunity even when the business’s PTET benefit is limited.
This doesn’t automatically make ECEP the better choice. It means we have another planning tool worth evaluating.
Comparing the Three New York SALT Tax Workarounds
Here’s a simplified comparison:
| Program | Tax Based On | Rate | Personal Tax Credit |
|---|---|---|---|
| NYS PTET | Qualifying pass-through income | Graduated, beginning at 6.85% | New York State |
| NYC PTET | Qualifying NYC pass-through income | 3.876% | New York City |
| NYS ECEP | Covered employee wages over $40,000 | 5% | New York State |
All three programs potentially provide a federal business-level tax deduction.
But the eligibility requirements, tax calculations, and personal credits differ.
And remember, ECEP is a New York State program. There is no separate New York City ECEP program.
Can You Use All Three New York SALT Tax Workarounds Together?
Potentially, yes.
Let’s look at an example.
Assume an eligible NYC S corporation owner has:
- $150,000 in annual W-2 compensation
- $100,000 in qualifying pass-through business profit
- New York City residency
- Eligibility for all three programs
For illustration, using the stated amounts as the separate tax bases before considering interactions:
| Program | Illustrative Tax |
|---|---|
| NYS PTET | $6,850 |
| NYC PTET | $3,876 |
| NYS ECEP | $5,500 |
| Total | $16,226 |
That represents $16,226 of potential entity-level tax payments, generally deductible federally, subject to the applicable rules and timing.
But it does not mean the owner saves $16,226 in taxes.
The actual federal benefit depends on the owner’s federal marginal tax rate, the interaction with the qualified business income deduction, and other factors.
The New York State and New York City credits also need to be calculated separately.
And because the three taxes can affect the business’s income and one another’s calculations, the final numbers may differ from this simplified example.
This is why we believe tax planning should involve an actual calculation, not just making every available election.
Election Deadlines: Timing Matters
These programs generally require an election before the tax year or early in the tax year.
For the 2027 tax year, the key election deadlines are:
| Program | Election Deadline |
|---|---|
| NYS PTET | March 15, 2027 |
| NYC PTET | March 15, 2027 |
| NYS ECEP | December 1, 2026 |
Notice the difference.
ECEP requires planning before the year begins.
That means if you’re considering ECEP for 2027, waiting until your 2027 tax return is prepared will be too late.
PTET also requires attention to estimated tax payments and other administrative requirements throughout the year.
How We Evaluate New York SALT Tax Workarounds for Clients
At My Fiscal Office, we don’t believe every available tax election is automatically a good idea.
For a New York business owner, we would generally compare the following scenarios:
- No elections
- NYS PTET and, if eligible, NYC PTET
- ECEP without PTET
- All applicable programs together
Then we look at the combined impact on the business and the owner.
We consider federal income tax savings, state and city credits, business profitability, shareholder compensation, estimated tax payments, and any administrative costs.
We also consider whether the owner can actually use the credits and whether the elections make sense based on expected future income.
The goal isn’t simply to create another business deduction.
The goal is to reduce your overall taxes without creating unnecessary complications or cash-flow problems.
Final Thoughts: Don’t Overlook These Tax Planning Opportunities
For New York business owners, particularly S corporation shareholders living in New York City, PTET and ECEP deserve a closer look.
NYS PTET provides a potential federal deduction tied to qualifying business income.
NYC PTET adds a separate city-level opportunity.
ECEP offers another approach based on employee wages.
Depending on your circumstances, one, two, or all three programs may be appropriate.
But the elections must be made on time, and the benefits should be calculated before you commit.
At My Fiscal Office, we believe the best tax planning happens throughout the year, not when we’re rushing to complete a return.
Considering whether your business should elect PTET or ECEP? Contact My Fiscal Office to discuss your options.
This article is for general educational purposes and is not individualized tax advice. Eligibility, tax rates, credits, and election requirements depend on your circumstances and the applicable tax year. Confirm current requirements with your tax professional or the New York State Department of Taxation and Finance before making an election.